Hot CPI, low hike odds: inflation is energy, not core
The claim. The inflation data looks bad and the Fed odds look relaxed because they measure different things. Headline inflation is an oil story; core inflation, the part a rate hike can actually influence, has barely moved. The market is not betting the Fed is done. It is betting the Fed waits until December.
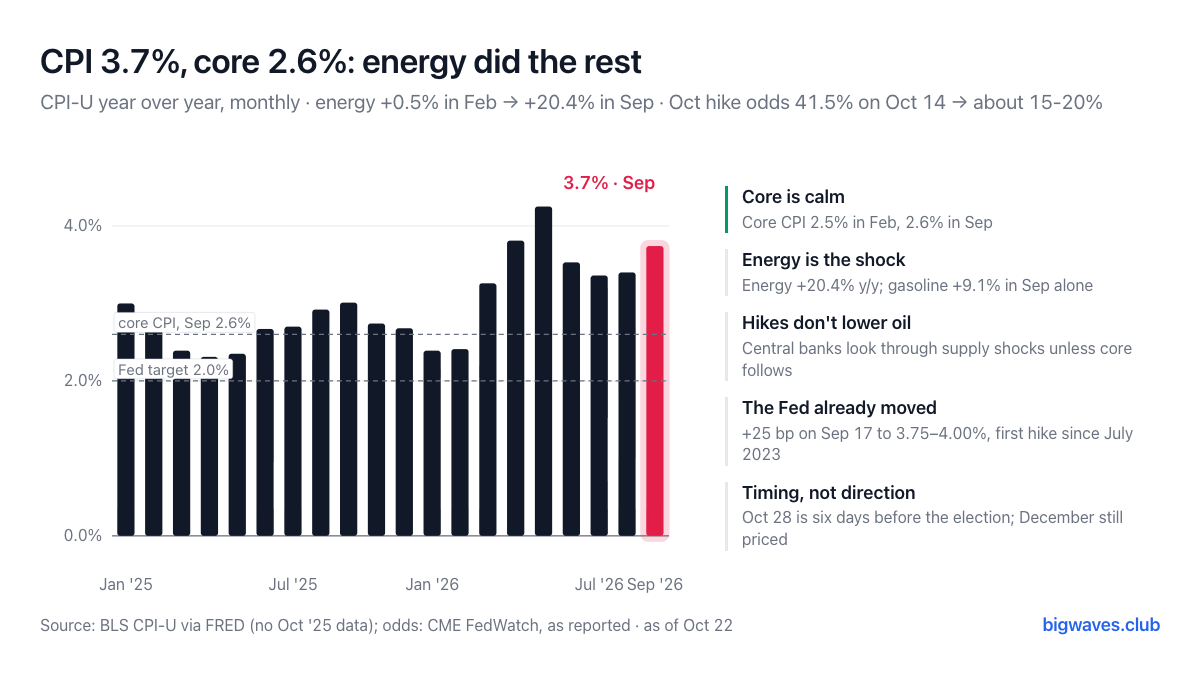 Caption: headline CPI by month. The dashed lines are September's core CPI (2.6%) and the Fed's 2% target. The gap between the red bar and the core line is mostly energy.
Why
- Core is calm. Core CPI was 2.5% a year in February and 2.6% in September. Headline went from 2.4% to 3.7% over the same months. Source: BLS CPI-U, not seasonally adjusted, via FRED; the October 2025 reading was never published because of the shutdown.
- Energy is the shock. The energy index went from +0.5% a year in February to +20.4% in September. Gasoline rose 9.1% in September alone, more than half of the month's 0.6% headline gain. Producer prices tell the same story: PPI final demand +1.3% in the month and +6.3% a year.
- Rate hikes do not make oil cheaper. A supply shock lifts prices and slows growth at the same time. Central banks usually look through it unless it spreads into core prices and wage expectations. Five-year breakeven inflation is 2.45%, which says the market does not think it has yet.
- The Fed already moved. It raised the target range by 25 bp on September 17 to 3.75-4.00%, its first hike since July 2023, after three cuts in late 2025. One hike has already been delivered for this shock.
- The calendar argues for waiting. The October 28 meeting is six days before the November 3 election, and the Fed has hiked that close to an election once since 1990. Meanwhile financial conditions tightened on their own: the 10-year yield is 5.13%, and the AI-led selloff has QQQ down 4.8% in October.
The odds, in numbers
| Date | October 28 hike odds | Source |
|---|---|---|
| Late August | about 9% | CME FedWatch, as reported |
| October 14, after CPI | 41.5% | CME FedWatch, 12:20 pm ET |
| October 19-21 | about 12-20% | CME FedWatch; Kalshi/Polymarket average |
| December 9 meeting | a hike still widely expected | press reports of FedWatch |
What we expect
- Base case (to December 9): the Fed holds on October 28 and hikes on December 9, as long as core CPI stays below 3% in the October and November reports. Signal it is working: the October 28 statement keeps the tightening bias and core CPI prints 0.3% or less on November 10.
- Alternative: oil falls back and core cools, and December's hike is priced out too. Signal: WTI back under $90 and core CPI at 0.2% or less on November 10.
What would change our mind
- Core picking up. Core CPI's three-month annualized pace rose to 3.4% in September from 2.0% in August, and core PPI is +5.0% a year. If November 10's core CPI is 0.4% or more, the "it's just energy" case fails, and an October-style surprise becomes a December certainty, with talk of more.
- An October hike anyway. The Fed says it does not plan around elections. A hike on October 28 would mean it sees second-round effects the market does not.
This note is general information and the author's opinion as of the date shown. It is not investment advice and does not consider your situation. The author may hold positions in the securities discussed. Data are from the sources named and may contain errors; past performance does not predict future results. Do your own research.