Meta: three straight post-earnings selloffs, first in 20 reports
by BigWavesAlso available in Chinese · switch language in the footer
The claim. Meta is beating on revenue and getting sold on spending. Three reports in a row the stock has fallen on the next session, which has not happened in the 20 reports since 2022. The question each time was the same: how much more capital before the AI investment pays back, and who funds it.
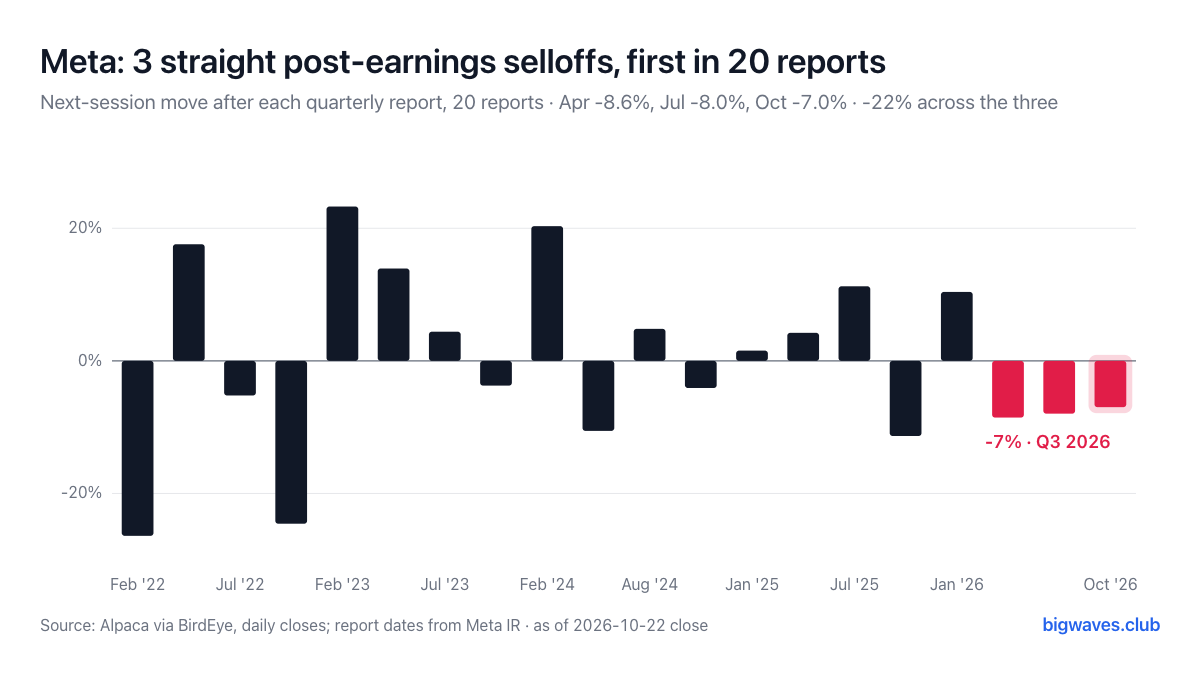 Caption: the move in the session after each earnings release. The three red bars are April, July and October 2026.
Why
- The streak is new. Next-session moves: -8.6% (Apr 30), -8.0% (Jul 30), -7.0% today, -21.7% compounded. In the 17 reports before them, the longest run of declines was two. Today's close of $648.85 is 16.6% below the Sep 24 high. Source: Alpaca daily closes via BirdEye, as of the Oct 22 close.
- The sales were fine. Q3 revenue $64.6B, +26% year on year. Ad impressions +10%, price per ad +14%. Q4 revenue guidance $73-76B. Source: Meta Q3 2026 release (8-K), Oct 21.
- The costs were not. Costs and expenses $51.6B, +68%. Operating margin 20% against 40% a year ago. Capex $34.9B in the quarter. Free cash flow -$2.1B against +$10.6B a year ago, and no buybacks against $3.3B. The 2026 capex range moved to $135-145B and total expenses to $175-179B, with "aggressive" investment to continue into 2027.
- Two one-offs made it look worse. A $9.89B charge for the settlement with 52 attorneys general over teen mental health, which allows payments of up to about $18.6B. Without it, EPS was $7.40 against $3.83 reported. And a new non-voting Class C share, paid as a one-for-one dividend in January 2027, which works like a 2-for-1 split but gives Meta a way to issue stock without diluting control.
- Meta led a broad AI selloff. Today: META -7.0%, AMZN -4.6%, NVDA -4.4%, GOOGL -3.2%, MSFT -2.2%, QQQ -2.9%, SPY -1.2%.
What we expect
- Base case (to the Q4 report, late January): the stock tracks the 2027 capex number more than revenue. If January's guidance puts 2027 capex growth below 2026's and free cash flow back above zero, the streak ends with a positive reaction. Signal: a guidance range whose top end is below $175B.
- Alternative: 2027 capex is guided up again and Class C shares are issued to fund it. Then the pattern continues and the stock retests the April post-earnings low. Signal: any Class C issuance announced before the Q4 report.
What would change our mind
- Free cash flow turning positive in Q4 without a capex cut. That would mean revenue is outrunning the spending, the opposite of what the last three reactions priced.
- Peers diverging. If Alphabet, Microsoft and Amazon report similar capex increases next week and are not sold, the problem is Meta's funding mix, not AI spending in general.
This note is general information and the author's opinion as of the date shown. It is not investment advice and does not consider your situation. The author may hold positions in the securities discussed. Data are from the sources named and may contain errors; past performance does not predict future results. Do your own research.