French risk premium is the widest since January 2012
by BigWavesAlso available in Chinese · switch language in the footer
The claim. France's borrowing premium over Germany is back at euro-crisis levels, but this time it is a budget-and-ratings problem with dated catalysts, not a bank-funding problem. That makes the next four weeks unusually testable.
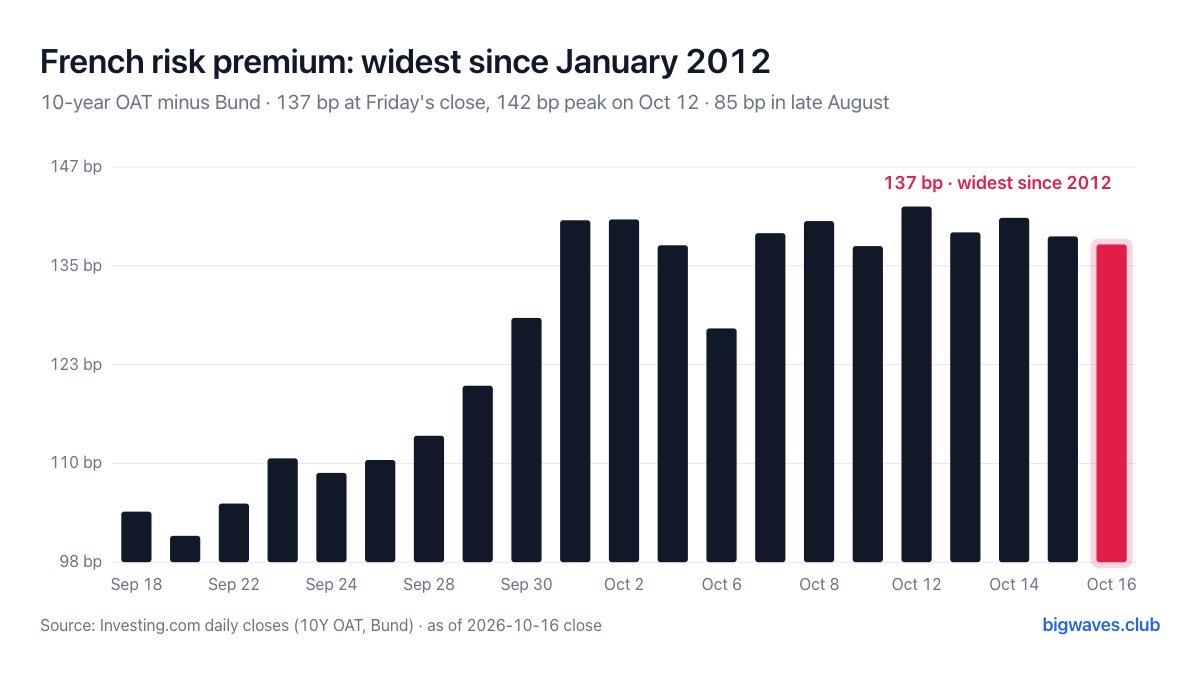 Caption: the spread between French and German 10-year yields, daily closes. Friday's 137 bp is the red bar; the Oct 12 close of 142 bp was the peak.
Why
- The spread has tripled in seven weeks. 85 bp at the end of August, 104 bp on Sep 18, 140 bp on Oct 1, a 142 bp peak on Oct 12, 137 bp on Friday. The last weekly close above Friday's level was the week of Jan 2, 2012, at 154 bp. Source: Investing.com daily closes, as of the Oct 16 close; weekly history since 1996 for the comparison.
- The move is France-specific. Since Sep 28 the Bund yield has fallen from 3.64 to 3.41 percent while the OAT went from 4.78 to 4.79 percent. The whole widening of the last three weeks is Germany rallying and France not following.
- The yield level is a 2008 level. The OAT closed above 4.85 percent on Oct 1 for the first time since June 2008 and traded above 5 percent on Oct 2, the highest since 2002.
- The arithmetic is known and dated. Deficit 5.4 percent of GDP this year, debt heading from 119.3 to 121.7 percent of GDP, about 3.81 trillion euros. The 2027 budget needs 54 billion euros of savings to reach 5.0 percent. The finance committee rejected the revenue package 31 to 3 on Oct 13; the first floor vote on it is Oct 20. Debt service rises about 12 billion euros a year.
- The ratings calendar is next. Fitch holds A+ stable, affirmed Aug 28 and warned on Oct 9. Moody's is Aa3 with a negative outlook and reviews on Oct 23. S&P at A+ follows on Nov 27.
What we expect
- Base case (4 weeks): if the Oct 20 vote passes the revenue package in recognisable form and Moody's holds at Aa3 on Oct 23, the spread settles into 115 to 130 bp. That is the Nov to Dec 2011 pattern, when the spread fell from 156 bp to about 105 bp within a month of the peak without any change in the fundamentals. Signal it is working: a close below 130 bp in the week after Oct 23.
- Alternative: if the package is gutted or rejected, or Moody's cuts to A1, the spread retests 150 bp and beyond, toward the Nov 2011 peak of 156 bp, and the 10-year revisits 5 percent. Signal: a close above the Oct 12 high of 142 bp before Oct 23.
What would change our mind
- A government collapse or dissolution. That turns the spread into a political-event trade rather than a budget trade. The 2024 snap-election spike to 86 bp happened in six sessions, faster than any vote calendar.
- An ECB backstop. Any hint that the Transmission Protection Instrument applies to France would cap the spread regardless of the vote. There has been none; Lagarde's line is that "the primary and first solution lies at home in France."
This note is general information and the author's opinion as of the date shown. It is not investment advice and does not consider your situation. The author may hold positions in the securities discussed. Data are from the sources named and may contain errors; past performance does not predict future results. Do your own research.